
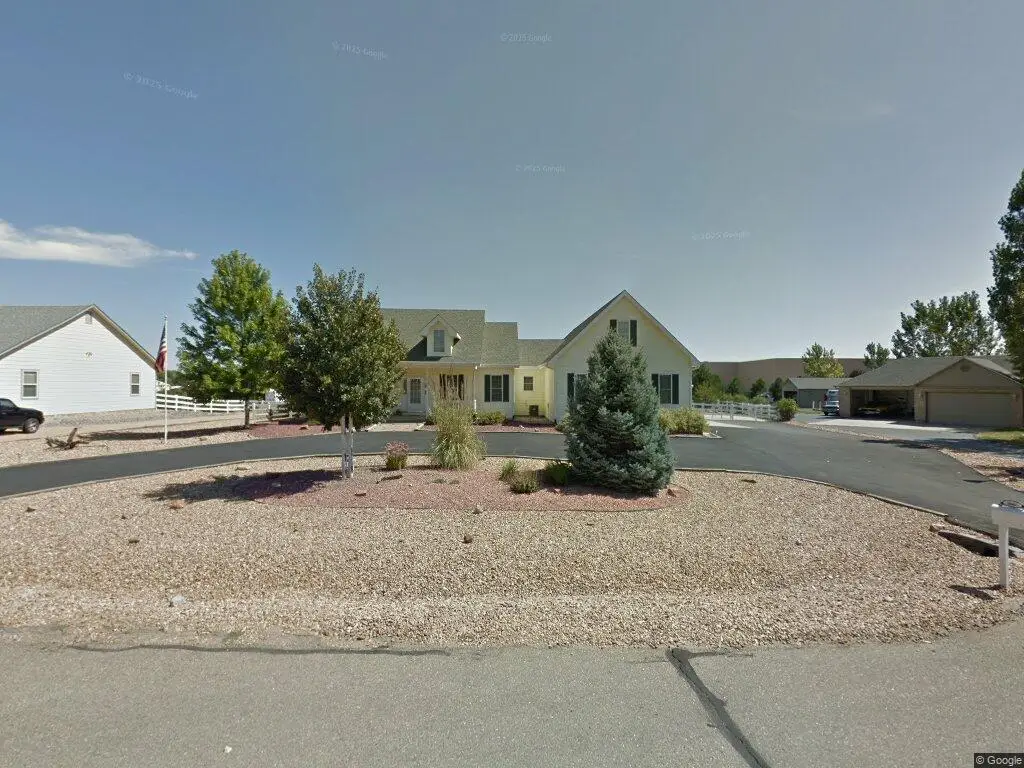
A VA cash out refinance just closed in Frederick, Colorado, giving a veteran homeowner access to the full equity in their million-dollar single family home. This loan funded on September 14, 2026, and it demonstrates one of the most powerful benefits available to those who have served: the ability to refinance up to 100 percent of a home’s value without requiring any remaining equity at closing.
Let me walk you through how this loan came together and what it can teach you if you are considering a similar path.
How a VA Cash Out Refinance Works
A VA cash out refinance allows eligible veterans, active duty service members, and surviving spouses to replace their current mortgage with a new VA loan while pulling cash from the equity they have built. Unlike conventional cash out options that typically cap at 80 percent of the home’s value, VA loans can go all the way to 100 percent loan to value in many cases.
For this Frederick homeowner, the property appraised at approximately $1,010,000, and the new loan matched that amount exactly. That means they were able to access a significant amount of cash while still maintaining ownership of their home as a primary residence.
The loan program used here was a 3/1 Treasury ARM VA with a 30 year term. An adjustable rate mortgage like this one starts with a fixed rate period, in this case three years, before the rate adjusts annually based on Treasury index movements. This structure can work well for homeowners who plan to refinance again, sell, or who simply want lower initial payments during that fixed window.
Who This Type of Loan Fits
This financing makes sense for veterans who have built equity in their homes and need access to that money for any number of purposes. Common reasons include consolidating higher interest debt, funding home improvements, covering education costs, or simply having reserves available for life’s unexpected turns.
The borrower in this transaction had owned the home and built up value over time. By refinancing through the VA program, they were able to tap into that value without the stricter equity requirements that conventional loans impose.
If you are a veteran in Frederick or anywhere in Colorado exploring your options, understanding that VA loans offer this flexibility can open doors that other programs simply cannot.
A Quick Look at Frederick and Broomfield County
Frederick sits in a unique spot in Colorado, technically part of Broomfield County for this property, though the town spans multiple counties. The area has grown steadily over the past decade, attracting families who want access to both Denver and Boulder without the price tags of those urban cores.
Home values in Frederick have appreciated considerably, which is exactly why cash out refinancing has become such a relevant conversation for local homeowners. If you purchased or refinanced a few years ago, you may be sitting on more equity than you realize. For veterans in particular, the VA cash out option can help you put that equity to work.
What Moved This Loan Forward
From application to clear to close, this file took 43 days. The full funding happened at the 54 day mark. While every loan moves on its own timeline based on the specifics involved, there are some universal steps that help things progress smoothly.
First, having documentation ready from the start makes a real difference. VA loans require a Certificate of Eligibility, and if you do not already have one, your loan team can typically order it. Beyond that, standard items like tax returns, bank statements, and proof of homeowners insurance should be organized and accessible.
Second, responsiveness matters. When the underwriting team asks a question or requests a clarification, quick replies keep the file moving. I emphasize communication with every client I work with because I have seen firsthand how a slow response can add days or even weeks to a timeline.
Third, appraisal coordination is key. For a property in this value range, the appraisal process involves careful review. Making sure the home is accessible for the appraiser and providing any relevant information about recent improvements can help support the valuation.
The Value of Working with Someone Who Knows VA Loans
VA loans have specific requirements and nuances that not every lender handles regularly. From funding fee calculations to occupancy rules to the documentation unique to military service, experience matters. I have worked with many veterans navigating these exact questions, and I genuinely enjoy helping people understand their options in a way that feels clear and manageable.
Buying or refinancing a home is one of the biggest financial decisions you will ever make. It deserves more than a cookie cutter approach. It deserves a conversation that starts with listening and ends with you feeling confident about the path forward.
Terms vary by borrower, and all loans are subject to credit approval and underwriting guidelines. What happened on this file reflects this specific transaction, not a guaranteed outcome for every application.
Frequently Asked Questions
Can you do a VA cash out refinance up to 100 percent of home value?
Yes, VA cash out refinances can go up to 100 percent loan to value in qualifying situations, unlike conventional loans that typically cap at 80 percent. This allows eligible veterans to access their full home equity. Approval depends on individual circumstances and underwriting requirements.
What is a 3/1 Treasury ARM VA loan?
A 3/1 Treasury ARM VA loan has a fixed interest rate for the first three years, then adjusts annually based on the Treasury index. This structure can offer lower initial payments compared to a fixed rate mortgage. It works well for borrowers who may refinance or sell before the adjustment period begins.
How long does a VA cash out refinance take to close?
Timelines vary by file, but this particular VA cash out refinance in Frederick, CO moved from application to clear to close in 43 days and funded at 54 days. Factors like documentation readiness, appraisal scheduling, and response times all influence the overall timeline.
Who qualifies for a VA cash out refinance?
Eligible veterans, active duty service members, and certain surviving spouses can qualify for a VA cash out refinance. You must have a valid Certificate of Eligibility and meet lender requirements. All loans are subject to credit approval and underwriting guidelines.
Are home values in Frederick, CO high enough for cash out refinancing?
Frederick, Colorado has seen significant home value appreciation in recent years, making many homeowners candidates for cash out refinancing. This particular property appraised at approximately $1,010,000. A current appraisal will determine how much equity you can access.
Work with Duke Gallo
If you are a veteran in Frederick or anywhere in Colorado wondering whether a VA cash out refinance might work for you, I would love to have that conversation. Let me listen to your situation and help you understand your options in a way that actually makes sense.
- Website: www.emortgagecapital.com/team/Duke-Gallo-4239
- Email: dukeg@emortgagecapital.com
- Phone: (949) 688-5959
Duke Gallo, Vice President. NMLS# 2084855. E Mortgage Capital NMLS# 1448987. Loan terms vary by borrower and all loans are subject to credit approval and underwriting. This is not a commitment to lend. Equal Housing Lender.