
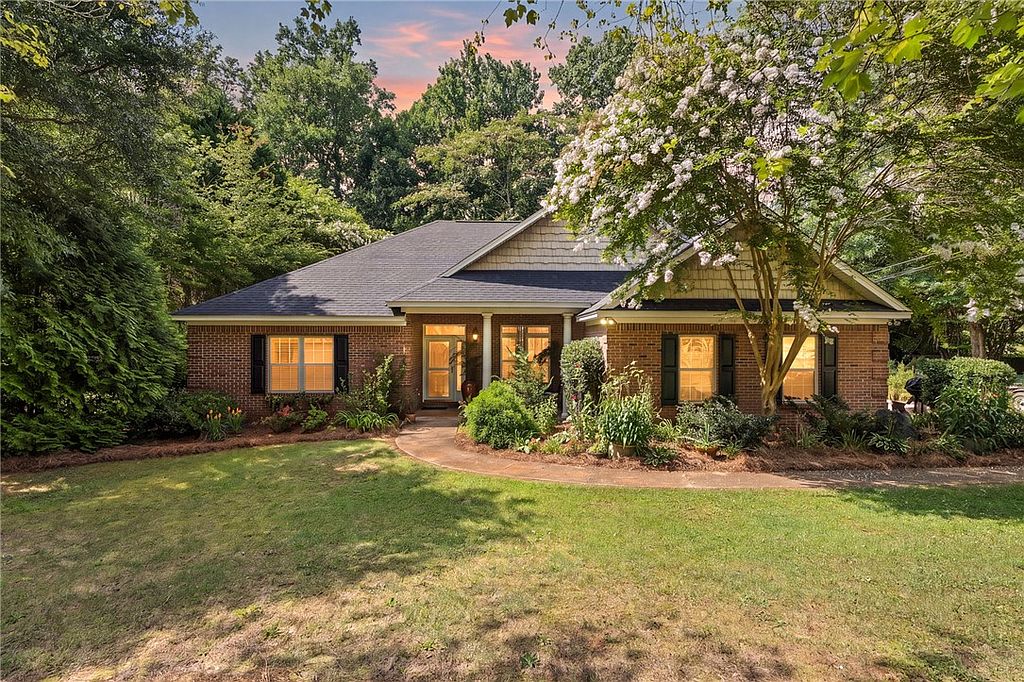
E Mortgage Capital recently funded a conventional 30 year fixed purchase loan for a single family home in Auburn, Alabama. The property, located in Lee County, had an approximate purchase price of $435,000 with a loan amount around $345,000. The buyer put down about 20 percent, resulting in a loan to value ratio of approximately 80 percent. This file moved from application to clear to close in 22 days and funded on September 14, 2026, just 26 days after the initial application.
This closing represents a straightforward path to homeownership using one of the most popular financing options available. For readers considering a similar purchase in Auburn or anywhere else, here is a closer look at how conventional financing works and what helped this particular transaction move smoothly.
Understanding the Conventional 30 Year Fixed Loan
A conventional loan is mortgage financing that is not backed by a government agency like the FHA or VA. Instead, these loans follow guidelines established by Fannie Mae and Freddie Mac. The 30 year fixed program locks in the same interest rate for the entire life of the loan, which gives borrowers predictable monthly payments over three decades.
This loan type tends to work well for buyers who have solid credit histories, stable income, and enough savings for a down payment. In this case, the buyer chose to put down approximately 20 percent. That 20 percent threshold is significant because it typically allows buyers to avoid private mortgage insurance, which is an added monthly cost on conventional loans with smaller down payments.
The conventional route offers flexibility too. It can be used for primary residences like this one, but also for second homes and investment properties. Loan amounts can range from modest to jumbo territory depending on the property and the local conforming loan limits.
A Quick Look at the Auburn Housing Market
Auburn sits in Lee County in east central Alabama and has grown steadily over the years. The presence of Auburn University creates consistent demand for housing, from students and faculty to families who simply appreciate the quality of life here. The city blends a college town atmosphere with a strong sense of community, making it attractive to first time buyers, growing families, and retirees alike.
Single family homes in Auburn range from charming older properties near downtown to newer construction in developing neighborhoods. For buyers using conventional financing, the market offers a good mix of options within conforming loan limits. Understanding what you can afford and getting pre-approved early can give you an advantage when competing for homes in desirable areas.
What Helped This File Close in 26 Days
Every loan file has its own timeline, and results vary based on individual circumstances. That said, there are a few things that often help transactions move efficiently. This file benefited from solid preparation upfront.
First, having documentation ready from the start makes a real difference. Lenders typically need pay stubs, tax returns, bank statements, and identification. When borrowers gather these materials before applying, the review process can begin right away without delays waiting on paperwork.
Second, responsiveness matters. Throughout the underwriting process, questions come up. Conditions get requested. The faster a borrower can provide what is needed, the faster the file keeps moving. This buyer stayed engaged and turned things around quickly when additional information was required.
Third, working with a loan officer who communicates clearly helps keep everyone on the same page. From the real estate agent to the title company to the borrower, coordination is key. When expectations are set early and updates flow regularly, surprises are minimized.
Finally, a clean appraisal and title search help avoid last minute issues. While buyers cannot control every variable, choosing a well maintained property in a stable neighborhood can reduce the chances of unexpected findings during due diligence.
Is a Conventional 30 Year Fixed Right for You
This program is worth considering if you are looking for stability and plan to stay in your home for a number of years. The fixed rate structure protects you from payment increases if market rates rise. And if you can manage a 20 percent down payment, you avoid the added cost of mortgage insurance.
Of course, every situation is different. Terms vary by borrower, and all loans are subject to credit approval and underwriting guidelines. What worked for this Auburn buyer may look different for someone else based on their financial profile and goals.
If you are thinking about purchasing a home in Auburn or anywhere else in Alabama, taking time to understand your options is an important first step. Conventional financing remains a strong choice for many buyers, and the 30 year fixed term continues to be the most popular structure for good reason.
Frequently Asked Questions
What is a conventional 30 year fixed mortgage?
A conventional 30 year fixed mortgage is a home loan not backed by a government agency that features a consistent interest rate and payment over 30 years. This structure provides long term stability and predictability for homeowners who want to budget confidently.
How much down payment do I need for a conventional loan?
Conventional loans typically require a minimum of 3 to 5 percent down, though putting down 20 percent allows you to avoid private mortgage insurance. The right amount depends on your savings, monthly budget, and overall financial goals.
How long does it take to close on a conventional purchase loan?
Closing timelines vary by file, but many conventional purchase loans close within 30 to 45 days. This particular loan in Auburn funded in 26 days from application, though individual results depend on documentation, responsiveness, and property factors.
Can I use a conventional loan to buy a home in Auburn, AL?
Yes, conventional loans are available for home purchases in Auburn, Alabama, and throughout Lee County. These loans work for primary residences, second homes, and investment properties within conforming loan limits.
What documents do I need to apply for a conventional mortgage?
You typically need recent pay stubs, W2s or tax returns, bank statements, and a valid ID to apply for a conventional mortgage. Having these documents ready before you apply can help speed up the process.
Work with Ty Tudhope
If you are considering a home purchase in Auburn or anywhere in Alabama, I would be glad to walk you through your financing options. Reach out when you are ready to start the conversation and explore what a conventional loan could look like for your situation.
- Website: www.emortgagecapital.com/team/Ty-Tudhope-5195
- Email: ttudhope@birchwoodlending.com
- Phone: (334) 703-3332
Ty Tudhope, Loan Officer. NMLS# 2430769. E Mortgage Capital NMLS# 1448987. Loan terms vary by borrower and all loans are subject to credit approval and underwriting. This is not a commitment to lend. Equal Housing Lender.