
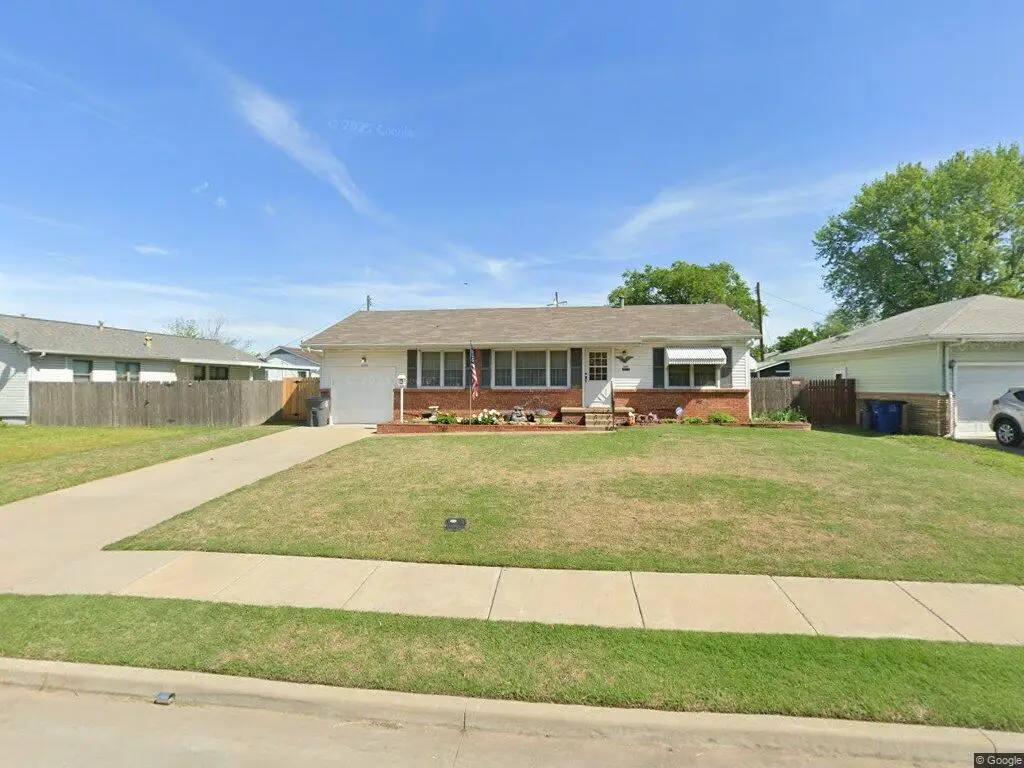
On September 4, 2026, E Mortgage Capital funded a cash out refinance on a single family investment property in Tulsa, OK. The loan closed under our Non-QM DSCR 30 Year Fixed program, providing the borrower with access to equity while maintaining a long-term fixed payment structure. The approximate loan amount came in at $135,000 against an appraised value of around $180,000, resulting in a loan to value of about 75 percent and leaving the homeowner with roughly 25 percent equity at closing.
This transaction highlights a financing option that continues to gain traction among real estate investors, particularly those who may not fit neatly into conventional lending guidelines.
Understanding Non-QM DSCR Loans for Investment Properties
DSCR stands for Debt Service Coverage Ratio. Unlike traditional mortgage programs that rely heavily on personal income verification, W-2s, and tax returns, a DSCR loan focuses primarily on whether the rental income from the property can cover the mortgage payment. This approach opens doors for self-employed investors, business owners, and others whose tax returns might not reflect their true financial strength.
The Non-QM designation simply means the loan falls outside the Qualified Mortgage rules established by federal regulators. These loans are not inherently riskier. They simply use different documentation standards and underwriting criteria to evaluate the deal.
For this Tulsa County file, the property’s ability to generate rental income relative to the proposed mortgage payment was a central factor in the approval process. The borrower was able to access cash from their equity without having to produce years of tax returns or detailed employment documentation.
Who Benefits From This Type of Financing
Investors with one rental property or a growing portfolio often find DSCR loans appealing. If your income looks complicated on paper or if your tax strategy involves significant write-offs, a conventional lender might struggle to approve you even when you have strong cash flow.
A cash out refinance through a DSCR program allows you to tap into the equity you have built in a rental property and redeploy that capital. Some investors use the funds for property improvements. Others put the money toward acquiring additional properties. The flexibility is part of what makes this program attractive.
The Tulsa rental market offers solid opportunities for investors looking to build or expand a portfolio. The city has a diverse economic base, a growing population, and a cost of entry that remains accessible compared to many metro areas. Whether you own property in midtown, south Tulsa, or the surrounding areas of Tulsa County, understanding your financing options can help you make smarter decisions about when and how to leverage your equity.
How This File Moved From Application to Funding
This particular transaction took 65 days from application to funding, with clear to close achieved at the 51-day mark. While every loan is different, this timeline reflects a file that stayed organized and responsive throughout the process.
Here is what generally helps a Non-QM DSCR file move smoothly:
Property documentation matters. Because the loan qualification centers on rental income, having a current lease agreement or documentation of market rents ready from the start helps the underwriting team assess the deal quickly. An appraisal will be ordered to confirm the value and often to support the rental income analysis.
Entity paperwork should be in order. Many investors hold rental properties in an LLC or similar structure. Having your operating agreement, articles of organization, and any required resolutions prepared can prevent delays.
Title and insurance need attention early. For a refinance, clearing title and ensuring proper insurance coverage are essential steps. Starting these conversations as soon as the application is submitted keeps the timeline moving.
Responsiveness is key. When the underwriting team requests additional items or clarification, quick turnaround times make a real difference. This file benefited from a borrower who stayed engaged and provided what was needed without extended back and forth.
Why Work With a Lender Who Knows Non-QM
Not every lender offers Non-QM programs, and not every loan officer understands how to structure them properly. At E Mortgage Capital, we work with investors across the country and have experience navigating the nuances of DSCR financing.
If you own investment property in Tulsa or anywhere else and you are curious whether a cash out refinance makes sense for your situation, the first step is a conversation. Every borrower’s circumstances are different, and all loans remain subject to credit approval and underwriting guidelines. What worked for this particular file may look different for yours, but understanding your options puts you in a stronger position to make informed decisions about your real estate investments.
Frequently Asked Questions
What is a Non-QM DSCR loan?
A Non-QM DSCR loan is a mortgage product that qualifies borrowers based on the rental income a property generates rather than personal income documentation like tax returns or W-2s. DSCR stands for Debt Service Coverage Ratio, which measures whether the property’s income can cover the loan payment. This program is popular among real estate investors who may have complex income situations.
Can I do a cash out refinance on an investment property in Tulsa?
Yes, cash out refinances are available for investment properties in Tulsa, OK through programs like Non-QM DSCR loans. These loans allow you to access the equity in your rental property without traditional income verification requirements. Approval depends on the property’s value, rental income potential, and other underwriting factors.
How long does a DSCR refinance take to close?
Closing timelines vary by file, but this Tulsa investment property refinance took 65 days from application to funding. Factors like property documentation, appraisal scheduling, title work, and borrower responsiveness all influence how quickly a loan can close. Each transaction is unique and subject to underwriting conditions.
What loan to value can I get on a DSCR cash out refinance?
Loan to value limits depend on the specific program and borrower qualifications, but this Tulsa file closed at approximately 75 percent LTV. That left the borrower with about 25 percent equity in the property after closing. Maximum LTV varies and all terms are subject to credit approval.
Do I need to show tax returns for a DSCR loan?
No, DSCR loans typically do not require personal tax returns for qualification. Instead, the lender evaluates whether the rental income from the property supports the mortgage payment. This makes DSCR financing attractive for self-employed investors or those whose tax returns show significant deductions.
Work with Jason Gilmore
If you are considering a cash out refinance on an investment property in Tulsa or elsewhere, I would be glad to walk through your options. Reach out and let us take a look at your situation together.
- Website: www.emortgagecapital.com/team/Jason-Gilmore-8298
- Email: jgilmore@emortgagecapital.com
- Phone: (918) 852-2559
Jason Gilmore, Division Manager. NMLS# 2454586. E Mortgage Capital NMLS# 1448987. Loan terms vary by borrower and all loans are subject to credit approval and underwriting. This is not a commitment to lend. Equal Housing Lender.